From Chapter 4 of The Last Salary
Mutual Fund Sahi
Nahi Hai.
For twenty years a single sentence sold India a future. It came with a jingle, a celebrity, and the soft authority of a fund house. It worked. Indians now pour ₹32,490 crore into SIPs every month¹ — a record, in September 2026.
This page is the argument your relationship manager will never make.
§ 01 · The thesis in one paragraph
A product designed to make fund houses rich cannot, in the same motion, retire you.
Mutual funds are not a scam. That would be too easy. They are something more durable: a good tool for one job — building a corpus — sold as the answer to a different one: replacing your salary, sold to a country that, for the first time in its history, has surplus salary and no instinct for what to do with it.
The arithmetic is not hidden. A regular-plan fee of about 1.5% a year, against 0.2% for a direct index fund, quietly takes ₹66 lakh — nearly a quarter of the final corpus — from a ₹10,000-a-month SIP over thirty years3. Investor behaviour takes more: over twenty years, investors who came in by lump sum earned 5.3 percentage points a year less than the very funds they owned4. And even a corpus that survives all of this still does not pay you a rupee until you start selling it.
§ 02 · Six arguments
Each is uncomfortable.
Together they are the case.
Read in any order. Each point is engineered to survive a long argument with a friend who works at an AMC.
- I.
The brochure return is not your return.
Axis Mutual Fund studied twenty years of Indian investors (2003–2022). Equity funds returned 19.1% a year. Investors who came in by SIP earned 15.2%. Investors who came in by lump sum earned 13.8%. The gap is behaviour — buying late, selling scared — and the brochure never prints it.4
Argument · I - II.
The fee is the most expensive small number in your life.
SEBI's caps on equity-fund expenses run from 2.10% a year for the smallest funds down to 0.95% for the largest, and since April 2026 GST and other levies are charged on top. In AMFI's data for March 2026, the median actively managed equity fund in a regular plan charged 1.93%; the median Nifty 50 index fund in a direct plan charged 0.18%. On a ₹10,000-a-month SIP over thirty years at 12%, a 1.5% fee instead of 0.2% leaves you ₹2.27 crore instead of ₹2.93 crore. The fee is charged in the crash years too.23
Argument · II - III.
SIP discipline is real. SIP outcomes are not the same thing.
Discipline of saving is a moral good. Discipline of saving into the wrong instrument still leaves you at 60 holding a number you cannot live on. The two get conflated on purpose.
Argument · III - IV.
“Long-term” is a slogan, not a strategy.
“Stay invested for the long term” is what you tell someone who has no other answer. A strategy specifies what you own, why you own it, what you'll do when it falls 40%, and what counts as enough. Most SIP advice specifies none of these.
Argument · IV - V.
Most paid experts do not beat the cheap index.
S&P's SPIVA India scorecard (Year-End 2025) found that over ten years 76.3% of actively managed large-cap funds and 79.0% of mid- and small-cap funds did worse than their benchmark index. You paid a professional, every year, and three times out of four the cheap basket that makes no decisions did better.5
Argument · V - VI.
A corpus is not an income.
A mutual fund pays you on exactly one day: the day you sell. Building the pile is the half of the story they advertise. Living on it — selling units every month in retirement — is the half they leave out. That half is next.
Argument · VI
§ 03 · The half they never showed you
The SIP builds it. The SWP eats it.
Every advertisement is about building the corpus. None of them is about living on it. In retirement you draw an income through a Systematic Withdrawal Plan — the fund sells a few of your units every month.
It sounds like the SIP in reverse. It is not. When you were buying, a falling market was your friend: your fixed amount bought more units. When you are selling, the same fall is your enemy: you must sell more units to raise the same rupees, and those units are gone for good. When the market recovers, it recovers on a thinner corpus. Researchers call this sequence-of-returns risk. Two retirees with the same average return can end up nine years apart, depending only on whether the bad years came first.
| Period | Fall from peak | Months below the old high |
|---|---|---|
| 2000–2001 (Dot-com) | about 56% | about 47 |
| 2008–2009 (Global financial crisis) | about 61% | about 34 |
| 2020 (COVID) | about 38% | about 10 |
| 2021–2022 (Rate hikes) | about 17% | about 13 |
Source: BSE Sensex historical data, approximate. Past market behaviour is not a guide to future results.
₹1 crore, withdrawing ₹75,000 a month and raising it 5% a year for prices, at a 6% return, runs out in 13 years. Retire at 60, and it is gone by 73 — and that assumes no crash.
The 4% rule was not built for India
The famous rule says withdraw 4% a year and your money lasts thirty years. It was built on American history, where inflation ran at 2–3%. Indian research by Ravi Saraogi and Rajan Raju found the safe rate here is closer to 3–3.5%. At that rate, ₹1 crore pays you about ₹25,000 a month. After thirty years of saving.6
Interlude
“The safest way to stay middle-class— Sagar Saroy, The Last Salary
is to invest like the middle class.”
§ 04 · Receipts
The numbers the jingle forgot.
Monthly SIP inflows, September 2026. A record high.
SEBI's highest cap on equity-fund expenses from April 2026, before GST and levies, which are now charged on top.
What a 1.5% fee costs versus a 0.2% index fund on a ₹10,000/month SIP over 30 years at 12%. About 23% of the corpus.
How far lump-sum investors trailed their own equity funds each year over 2003–2022. SIP investors trailed by about 4 points.
Indian large-cap funds that did worse than their benchmark over 10 years.
What ₹1 crore can safely pay you each month at the 3–3.5% withdrawal rate Indian research supports.
Every number above is sourced — see § Sources below. Fee figures are an illustration on stated assumptions; 12% is an assumption, not a guarantee.
§ 05 · Anticipated objections
Yes, we've heard them all.
“But SIPs beat FDs.”
Yes — the wrong benchmark. The question is not whether MFs beat the dumbest alternative. It is whether they are the best use of your highest-earning decade. Often, they are not.
“Index funds fix this.”
Partially. Index funds fix the fee problem. They do not fix the concentration-of-wealth problem, the tax drag, or the fact that you still don't own anything you control.
“So what should I do instead?”
Build income, not just a pile. Own something that pays you every month and grows while it does — that is the whole of The Last Salary. Cash flow, not corpus.
§ 06 · Who is saying this
I did exactly what I was told. Then I checked.
I'm Sagar Saroy. I spent twenty-nine years in corporate India. In 2007 an advisor showed me a SIP illustration with a jaw-dropping final number, and I paid it every month — through the 2008 crash, topping up, doing everything right. Four years later I extended my real returns forward and they did not come close to the promise. So I sold every mutual fund I held.
In 2012 I bought the smallest flat in the building, a 1RK, and turned it into a 1BHK so it rented like one. By 2015 the rent across my properties covered every EMI. By 2019 I was financially free. I left corporate life at fifty and wrote down what worked.
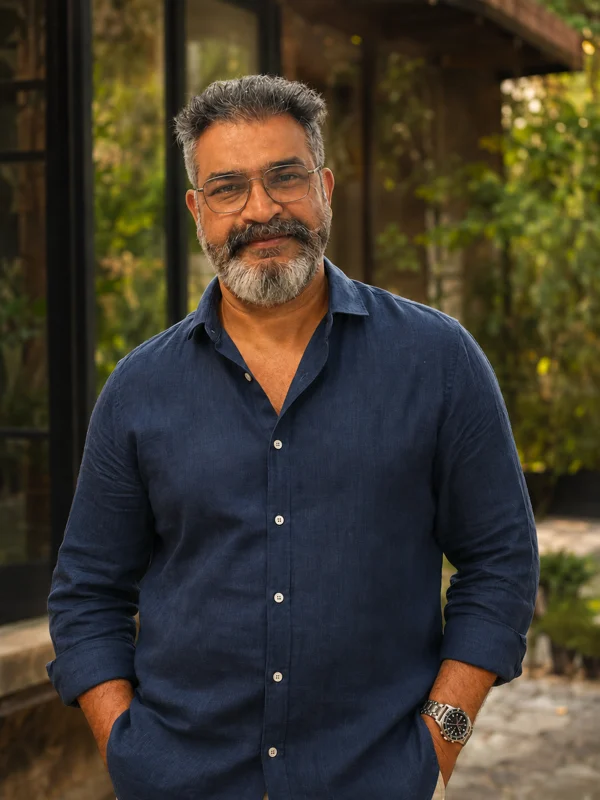
“The danger in retirement is not a market falling; it is being forced to sell when it does.”
— Sagar Saroy, quoted in The Economic Times · ET Wealth, 12 October 2026. ↗
§ 07 · Where the argument lives in full
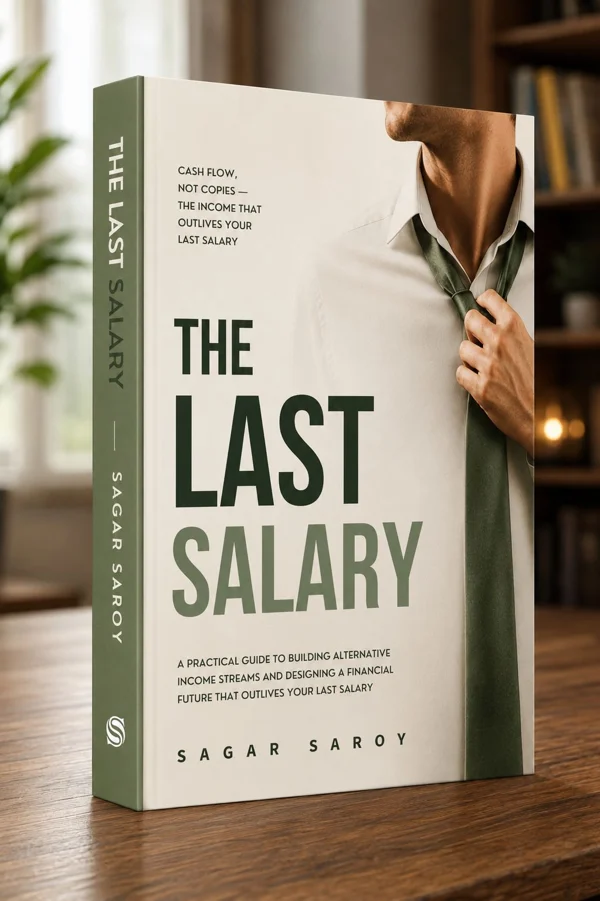
The Last Salary.
Cash flow, not corpus.
Chapter 4 of the book is called Mutual Fund Sahi Nahi Hai. This page is its short version. The book has the full numbers, the withdrawal maths, and the other half: how to build income that keeps arriving after your last salary.
- Why the SIP-and-chill consensus quietly fails the salaried
- What the wealthy actually own — and what they pointedly don't
- A framework for designing the salary you stop needing
Go deeper
Six short guides, one question each.
- SIP Real Returns: Why Your Return Is Not the Fund's Return
- Regular vs Direct Plan: The Small Fee That Costs ₹66 Lakh
- Active vs Index Funds: Do Indian Fund Managers Beat the Market?
- The SIP Builds It, the SWP Eats It: SWP Risk in Retirement
- Safe Withdrawal Rate in India: Why the 4% Rule Falls Short
- Corpus vs Cash Flow: Why a Big Number Is Not a Retirement Plan
§ 08 · For the skeptical
Questions we keep getting.
- Is this anti–mutual fund?
- No. Mutual funds are legal, regulated, and good at one job: building a corpus. The argument is that a corpus is not an income, and most people are sold one while needing the other.
- Should I stop my SIP?
- This page does not tell you to. It asks you to check what your SIP is for. If the goal is a monthly income that outlives your salary, ask how the corpus will pay you, at what withdrawal rate, and what happens if a crash comes in your first years of retirement.
- Is a regular plan really that expensive?
- In AMFI's March 2026 data the median active equity regular plan charged 1.93% a year and the median Nifty 50 index direct plan 0.18%. Over thirty years even a 1.5% vs 0.2% gap costs about a quarter of the final corpus on the same SIP.
- What is a safe withdrawal rate in India?
- Indian research by Ravi Saraogi and Rajan Raju puts it closer to 3–3.5% a year, not the American 4%. At 3%, ₹1 crore pays about ₹25,000 a month.
- Are you a SEBI-registered adviser?
- No. This is an argument and education, not investment advice. Talk to a qualified professional before acting.
- Who is Sagar Saroy?
- A former corporate executive (29 years) who stopped his SIPs after four years, built rental income from a single 1RK flat, and was financially free by 2019. Author of The Last Salary: Cash Flow, Not Corpus.
§ 09 · Sources
Show your work.
An argument without receipts is just a louder opinion. Every numeric claim on this page is traceable — to AMFI data, SEBI's rules, S&P's scorecard, published research, or the book's own calculation shown in the source note.
- 1.
AMFI monthly data for September 2026 (released 12 October 2026): SIP contributions ₹32,490 crore, a record high.
amfiindia.com ↗ - 2.
SEBI's revised mutual fund expense framework, effective 1 April 2026: equity scheme base expense ratio capped from 2.10% (smallest AUM slab) to 0.95% (largest); GST and statutory levies charged on top.
cafemutual.com ↗ - 3.
Author's calculation, The Last Salary, Chapter 4, Table 05: ₹10,000/month for 30 years at 12% gross, fees 0.20% vs 1.50%: ₹2.93 crore vs ₹2.27 crore. Median expense ratios from AMFI, Total Expense Ratio of Mutual Fund Schemes, 31 March 2026.
amfiindia.com · Expense ratio ↗ - 4.
Axis Mutual Fund, 'Analysis of Indian investor behaviour and its impact on performance', September 2022, covering 2003–2022: equity fund return 19.1%, SIP investor return 15.2%, lump-sum investor return 13.8%.
cafemutual.com ↗ - 5.
S&P Dow Jones Indices, SPIVA India Year-End 2025: over 10 years, 76.3% of Indian large-cap and 79.0% of mid/small-cap funds underperformed their benchmarks.
S&P · SPIVA India ↗ - 6.
Rajan Raju (Invespar) and Ravi Saraogi (Samasthiti Advisors), 'Balancing Acts: Safe withdrawal rates in the Indian context', 2024, using Indian data from 2000 to 2023: recommended safe withdrawal rate 3–3.5%.
business-standard.com ↗
Last verified: 17 October 2026.